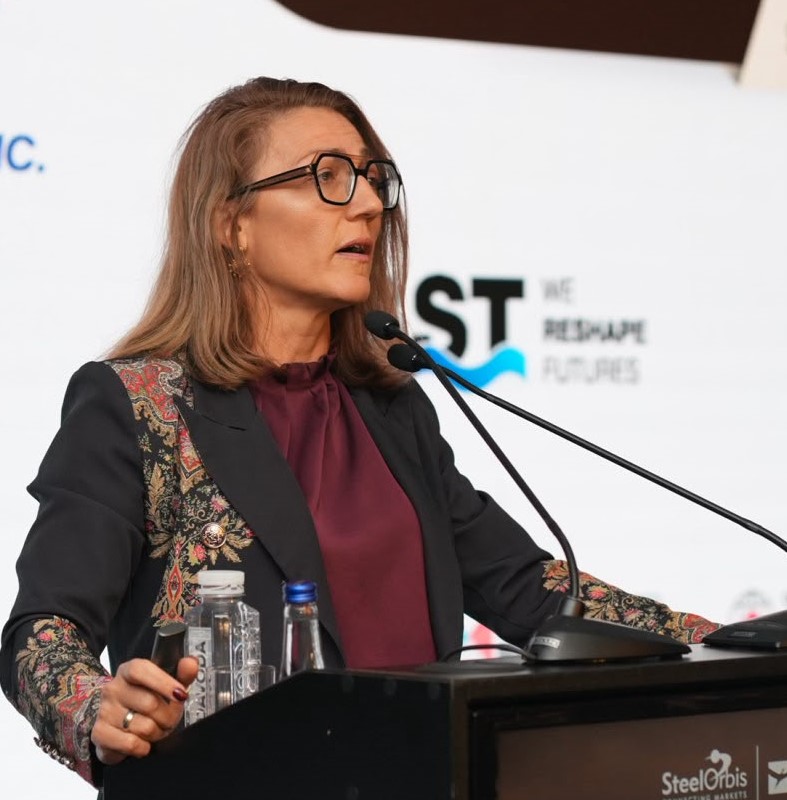
Geopolitical fragmentation is changing global steel trade: market access, supply chain reliability, and regulatory compliance are becoming increasingly important factors of competition along with production costs and prices, said Velina Cakarova, geopolitical strategist and founder of FACE, speaking at the SteelOrbis 2026 Autumn Conference and the 95th IREPAS meeting in Belgrade. On September 27-29, Ms. Chakarova stated that steel has to become a strategic asset, not just a trade item, as geopolitical competition increasingly extends to tariffs, sanctions, export controls, energy, logistics, and financial systems.
Excess capacity and trade barriers are changing global потоки
cf. Chakarova highlighted the combination of growing global steel overcapacity and rising trade barriers as a major problem. According to the data, global excess steel production capacity is expected to increase from about 640 million tons to 745 million tons by 2028, while the number of trade barriers has increased fivefold.
She stressed that protectionist measures can maintain margins in individual markets, but they do not eliminate surpluses to increase capacity or create additional demand. Instead, excess volumes are redirected to markets that remain accessible.
China is, she noted, central to this trend. Chinese steel exports reached 131.2 million tons in 2025, accounting for 40.8% of global exports, while 207 trade restrictions in 62 countries are currently aimed at protecting domestic steelmaking facilities.
The steel trade is becoming increasingly dependent on demands beyond prices. Tariffs and quotas, melting and bottling and provenance rules, carbon regulations such as CAM, sanctions, banking requirements, ship compliance, and route reliability can all determine whether a deal is possible. "Competition is now measured in tons, which are also customs cleared, rather than the tons that will leave the mill," Ms. Tchakarova said.
Europe is facing growing demand, but also a reduction in domestic производства
Europe is showing increasing tensions between protection and import dependence. Ms. Makarova said that steel demand in Europe increased by 4.4 percent in 2025, while domestic production decreased by 2.9 percent. Imports provide about 30% of demand, while about 75% of the region's iron ore and coking coal needs come from abroad.
Recalling the new EU and CBAM steel trade regime, Ms. Chakarova stressed that protection can lead to increased sustainability only if it is supported by competitive domestic production, including adequate energy, investments financing and reliable supply of raw materials.
Compliance and reliability determine конкурентоспособность
In a broader sense, by According to Makarova, she expects the steel market to turn into overlapping trading systems rather than completely separate blocks. Low-carbon, traceable, and affordable steel is likely to be sold in premium markets, while protected regional markets are increasingly favoring domestic or related manufacturing.
Chakarova concluded that under these conditions, steel with the lowest cost would not necessarily have a competitive advantage. Instead, market access will increasingly depend on the ability to provide a traceable, compliant, funded, insured, and reliable steel supply.
There are no comments yet.